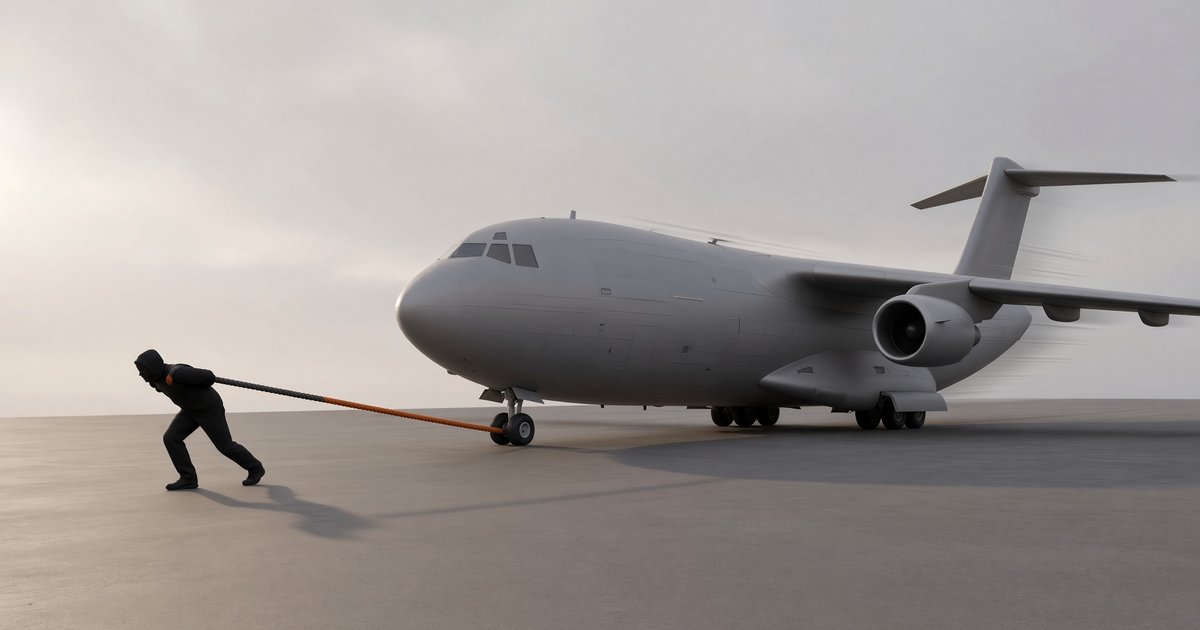
Watch a World’s Strongest Man competitor attempt the vehicle pull — a rope around their shoulders, a 200-tonne aircraft behind them, nothing but raw force between the two. For the first few seconds, nothing happens. The plane doesn’t move. It looks, frankly, impossible. Then, almost imperceptibly, it inches forward. Once it’s moving, everything gets easier — momentum starts doing part of the work that pure strength was doing alone.
Getting out from under financial pressure works the same way. When bills are piling up, the whole situation can feel like that stationary plane — heavy, unmoving, immune to effort. The 5 percent budgeting rule exists for exactly that moment: a way to get the plane moving without needing the herculean, all-at-once effort that usually stalls out before it starts.
Why cutting back 100% at once fails
Faced with a tight budget, the instinct is to go big — cancel everything non-essential, cut every category to the bone, all in one dramatic pass. It rarely lasts. Big, sudden restriction tends to produce a burst of motivation followed by a crash a few weeks later, and the whole plan quietly gets abandoned. Most people who’ve tried to cut back “as far as they can go” have already discovered this the hard way.
The 5% rule works because it asks for almost nothing from any single category. Instead of eliminating something entirely, you’re just looking for a 5% reduction, everywhere, all at once. It’s small enough that you genuinely won’t notice most of the individual cuts — but applied broadly, the total adds up to something real.
The 5% rule, explained
The rule itself is simple: starting today, look at everything you spend money on and find a 5% reduction wherever you can. Not 50%. Not “cut it out entirely.” Just 5%, applied as widely as possible. You can even treat it as something of a game — a daily hunt for small, barely noticeable trims rather than one painful negotiation with yourself.
The reason this works is that almost everything in daily life carries a hidden cost we’ve stopped noticing, simply because we don’t pay for it item by item. Heating, lighting, water, wear on clothes and furniture — it’s all there, quietly adding up, and a 5% trim on each is rarely something you’d consciously feel.
Finding hidden 5%s in daily life
Start with the categories that feel free but aren’t. Streaming and app subscriptions are an easy first stop — a 5% cut might mean dropping one tier, or cancelling a service you signed up for and forgot about. Utility bills are another: turning the thermostat down by a single degree, switching off devices at the wall overnight instead of leaving them on standby, or hanging washing instead of running the dryer every load.
- Subscriptions — audit everything you’re paying for monthly; cancel or downgrade the one you use least.
- Utilities — a one-degree thermostat adjustment, unplugging idle devices, shorter showers.
- Groceries — buying the store-brand equivalent for just a few regular items, using slightly less of liquid products like detergent or shampoo per use.
- Insurance and phone/internet plans — call your provider at renewal time and ask directly whether a better deal exists.
Five percent is negligible on its own. You won’t even notice it. But once you’re doing it across electricity, fuel, food, and subscriptions all at the same time, it stops being negligible.
Where to look first
Fuel is another category most people overlook. Removing unnecessary weight from the car — sports gear, tools, anything that doesn’t need to be there — genuinely improves mileage, since carrying extra weight costs extra fuel. Driving a little more smoothly, and not filling the tank all the way every time, both shave a small percentage off fuel costs without changing how much you actually drive.
Insurance renewals deserve particular attention, because most providers count on inertia — the assumption that customers won’t shop around at renewal time. A single phone call, checked against a couple of competitor quotes, often finds a saving well above 5% on its own, for exactly the same coverage.
What happens once the plane starts moving
The real value of the 5% rule isn’t the first round of cuts — it’s what happens next. Once those small savings start accumulating, you’re in a position to reinvest them: paying slightly more than the minimum on a credit card each month, buying pantry staples in bulk when they’re on offer, or finally affording the switch to lower-energy light bulbs that pay for themselves over time. Each of those moves creates further savings, which compound into the next round.
This is the momentum stage — the plane isn’t just moving anymore, it’s rolling under its own weight, and each push gets a little easier than the last. It won’t feel dramatic in week one. Most people don’t notice real traction until a month or two in, once several small 5% cuts have stacked on top of each other. If you want a more detailed, category-by-category version of this same principle, our guide to advanced budgeting techniques walks through exactly how to track where those savings are coming from.
Five percent doesn’t sound like much. It isn’t supposed to. That’s the entire point — it’s small enough to actually start, and starting is the part that gets that 200-tonne plane moving in the first place.